For HR, payroll, finance and compliance teams · Updated November 2026
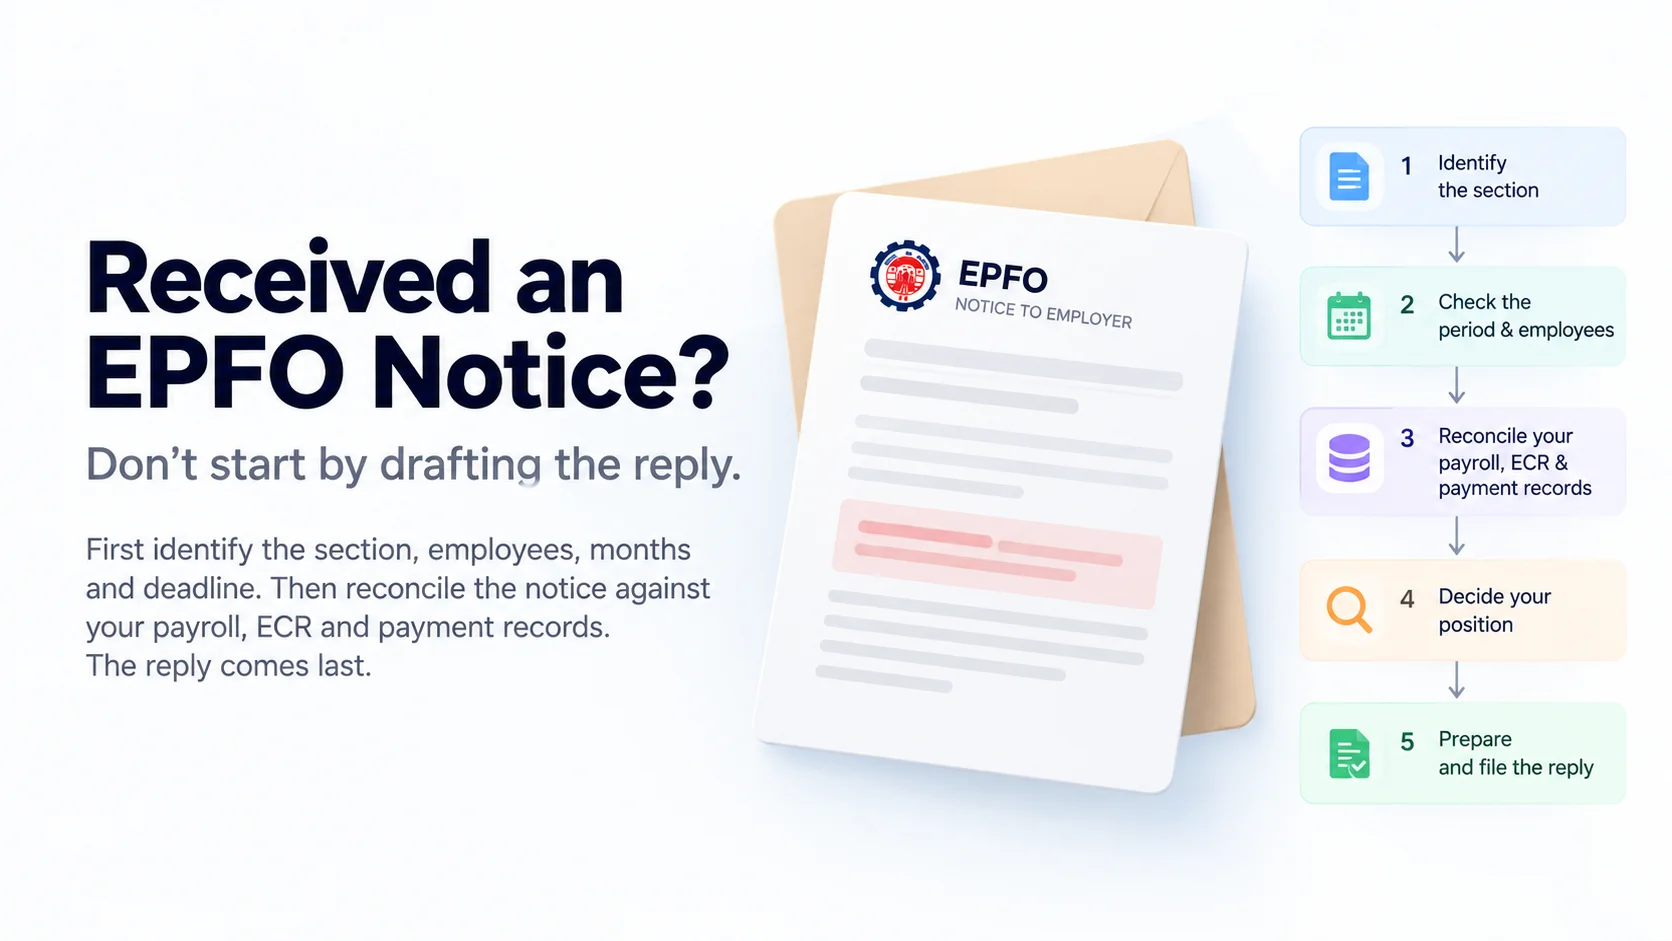
Received an EPFO notice? Do not start by drafting the reply.
Since 21 November 2025, EPFO notices to employers are issued under the Code on Social Security, 2020, not the EPF Act. A Section 125 notice (the successor to Section 7A) starts a judicial inquiry. If you don't respond, EPFO can decide the dues on the records it already has.
Before writing anything, identify the section, the period, the employees named and the hearing date. Then check those against your payroll, ECR and payment records. The reply comes last.
| Question | Short answer |
|---|---|
| Is Section 7A still used? | Section 7A was replaced by s.125 of the Code from 21 Nov 2025. Old proceedings continue under transition rules. |
| How far back can EPFO go? | No s.125 inquiry can start more than 5 years after the amount fell due. |
| What if I miss the hearing? | EPFO can decide on the records it has. You get 3 months to apply to set that order aside. |
| What does an appeal cost? | 25% of the assessed amount as pre-deposit, with no power to waive it. |
| Can damages be settled? | For defaults before 14 June 2024, yes, under VISHWAS 2026, until 28 Dec 2026. |
What is an EPFO notice to an employer?
An EPFO notice to an employer is an official communication asking an establishment to provide information, explain a discrepancy, attend a hearing, or pay or contest an amount under its provident fund obligations.
A notice states EPFO's position. It does not prove that every allegation, employee or amount in it is correct. Your reply should rest on what your own records show for the employees and months named.
Which notice did you receive?
Read the section number first. It tells you what is at stake and what happens if you do nothing.
| Notice | Code section (old EPF Act) | What it means | If ignored |
|---|---|---|---|
| Assessment or inquiry | s.125 (s.7A) | EPFO is deciding whether PF applies, or how much is due. It is a judicial proceeding with civil-court powers. | Dues decided on the records available (s.125(5)) |
| Damages | s.128 (s.14B) | Penalty for late or unpaid contributions, up to 100% of the arrears. Can only be levied after a hearing. | Levied without your side heard |
| Interest | s.127 (s.7Q) | Simple interest at 12% a year from the due date until payment (S.O. 2698(E), 29 May 2026). Not discretionary. | Keeps accruing |
| Direction to comply | s.137 (none) | A written chance to fix a violation within a set period before prosecution. | Prosecution. No second direction if the same violation repeats within 3 years. |
| Inspection or call for records | s.122 (s.13) | An Inspector-cum-Facilitator asks for records, increasingly online. | Can escalate to a s.125 inquiry |
| Show cause, ECR or default query | EPF Scheme 2026 | A request to explain or correct specific data or a missed payment | Can escalate to s.125 or s.128 |
Proceedings that began under the old Act continue under the Code's transition rules. Inquiries pending on 21 November 2025 must conclude by 20 November 2027.
Deadlines and limits under the Code
The Code changed the timing rules employers relied on under the EPF Act. These are the limits that decide most notice strategies.
| Question | Answer | Source |
|---|---|---|
| How far back can EPFO assess? | No inquiry may start more than 5 years after the amount fell due. Section 7A had no limit. | s.125(1) |
| How long can an inquiry run? | Target of 2 years, extendable by 1 year with recorded reasons | s.125(2) |
| What if I miss the hearing? | The officer can decide on the evidence and records already available | s.125(5) |
| Can I undo an ex parte order? | Apply within 3 months, showing the notice was not served or you had sufficient cause | s.125(6) |
| What does appealing an assessment cost? | 25% of the amount determined, deposited before the Tribunal hears it, with no waiver power (was 75%, waivable) | s.23(3) |
| What does appealing damages cost? | No pre-deposit on the face of the section | s.23(3) |
| Can old damages be settled? | Yes, for defaults before 14 June 2024, under VISHWAS 2026 until 28 Dec 2026. Interest must be paid first; pending appeals then end. | EPF Scheme 2026 |
| Whose assets are recovered first? | The establishment's property, then the employer's own | s.129 |
How serious is your notice?
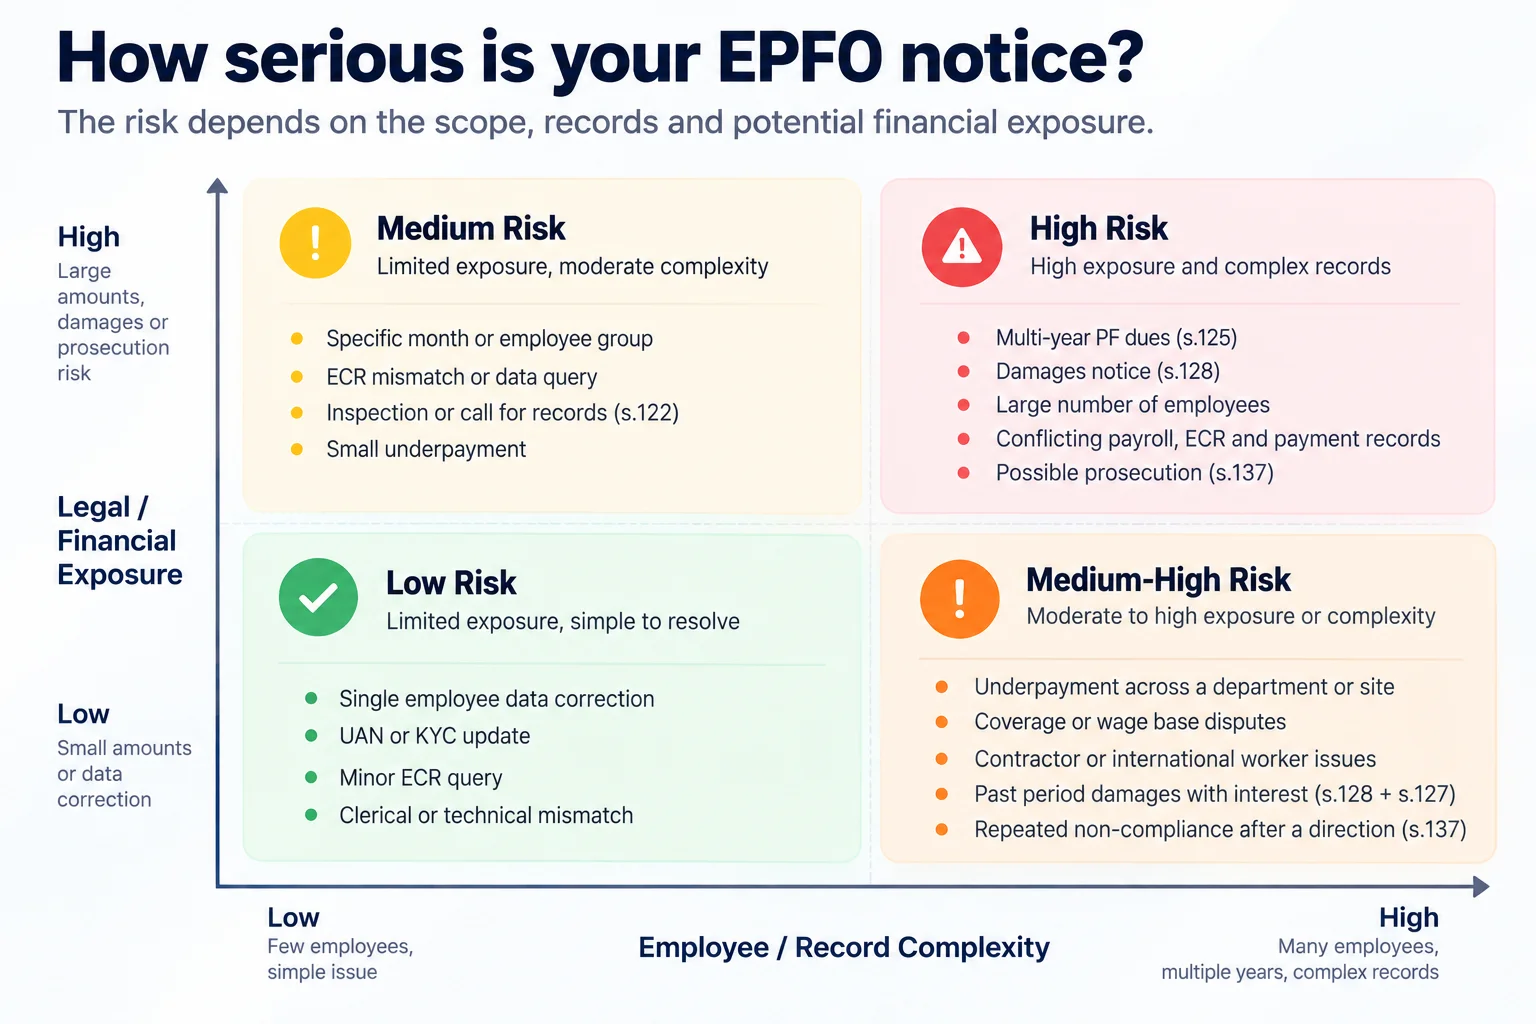
The section tells you the type of risk; five signals tell you how much work the reply needs. The more signals in the right-hand column, the less safe it is to reply before a full reconciliation.
| Signal | Lower complexity | Higher complexity |
|---|---|---|
| Deadline | Two weeks or more to the reply or hearing | Hearing within days, or already missed |
| Scope | One employee, one period | Many employees or several establishments |
| Period | Recent months, records at hand | Several years back, or before a payroll or consultant change |
| Exposure | Clarification or data correction | Dues, interest, damages or prosecution (s.125, s.127, s.128, s.137) |
| Evidence | Payroll, ECR and payment agree | Records conflict, are missing, or sit with a previous consultant |
The Kustodian Notice Reconciliation Test
Kustodian's Notice Reconciliation Test: before replying, settle what EPFO alleges, for which months and employees, which records prove it, and whether the allegation is correct, incorrect, partly correct or unresolved.
| Step | Question | Where the answer comes from |
|---|---|---|
| 1. Claim | What exactly is alleged, under which section? | The notice: office, reference number, section, deadline |
| 2. Period | Which wage months? | The notice, then your payroll calendar |
| 3. Population | Which employees, establishment or worker category? | The notice, matched to your HR master by UAN |
| 4. Evidence | Which records prove or disprove it? | The records table below |
| 5. Position | Correct, incorrect, partly correct or unresolved? | Your reconciliation of steps 2–4 |
The position decides the reply. Correct means pay or correct, and say so. Incorrect means contest with evidence. Partly correct means concede the supported part and contest the rest. Unresolved means ask for EPFO's documents or more time before taking a position.
Records to pull
Pull only what the allegation touches. For how these records connect, see the PF reconciliation chain.
| Record | Proves | Pull when |
|---|---|---|
| Payroll register | Wages and PF calculated | Contribution or wage is questioned |
| ECR files | What was declared to EPFO | Filing data is questioned |
| Challan, TRRN and bank statement | What was paid, and when | Default or delay is alleged |
| HR master, DOJ and DOE records | Who was employed, and when | Coverage or service period is questioned |
| UAN and Member ID report | Which account each employee maps to | An employee-level mismatch exists |
| Contractor ECRs and challans | Contract workers' PF | Contract labour is involved |
| Earlier EPFO correspondence | What was already explained or corrected | The matter has a history |
Worked example: "PF short for 12 employees"
Suppose a notice says contributions were short for 12 employees for April to June 2026 (illustrative). A reply saying "all PF has been paid" answers nothing. Instead, reconcile each employee-month:
| Reconciliation result | What it means | Employees (illustrative) |
|---|---|---|
| Payroll = ECR = payment | EPFO's observation is not supported | 10 |
| Payroll correct, ECR wage lower | ECR preparation error; genuine shortfall | 2 |
| Records missing | Ask for EPFO's basis before taking a position | 0 |
The reply concedes 2, pays the shortfall with 12% interest, and contests 10 with an employee-month table and challan copies. If the 2 errors share a cause, such as a payroll configuration change in April, fix that before May's ECR too. One wrong record is a correction; the same error across a cohort is a process problem.
How to structure the reply
A reply that addresses each allegation with evidence is harder to decide against than a general statement of compliance.
| Part | What it contains |
|---|---|
| 1. Reference | Notice number, date, section, establishment code |
| 2. Scope | The employees and months you accept as in scope, and any you dispute |
| 3. Reconciliation | An employee-month table: payroll wage, ECR wage, amount paid, TRRN |
| 4. Position | Correct, incorrect, partly correct or unresolved, for each allegation |
| 5. Action taken | Payments made, corrections filed, with dates |
| 6. Requests | Copies of EPFO's documents, a hearing, or time for unresolved items |
| 7. Annexures | Numbered evidence, each referenced in part 3 or 4 |
File it before the deadline, keep proof of submission, and attend the hearing with an authorised representative.
Five mistakes that make notices worse
- Missing the hearing. Under s.125(5), EPFO can decide on its own records. Setting that aside later needs an application within 3 months and a valid reason.
- Replying with a general statement. "PF has always been deposited" does not answer an allegation about specific employees and months.
- Treating a s.137 direction as routine mail. Its compliance period is your last chance to avoid prosecution, and the same violation within 3 years gets no second direction.
- Fixing one employee without checking the pattern. If the named employees share a joining batch, site or payroll migration, others are likely affected too.
- Answering an inquiry from memory. A s.125 inquiry is a judicial proceeding. Every statement should come from reconciled records.
When the notice points to a bigger problem
A notice often names a few employees from a problem that affects many. Use what it reveals to choose the next step.
| The notice reveals | Next step |
|---|---|
| Payroll and ECR do not match | ECR filing mistakes |
| Wrong date of joining | DOJ correction |
| Missing or wrong date of exit | DOE correction |
| Pension (EPS) record errors | Employer EPS errors |
| Damages for a pre-June 2024 default | VISHWAS 2026 |
| Years of unresolved errors | Historical PF errors |
| A previous consultant missed or mishandled it | PF consultant risk |
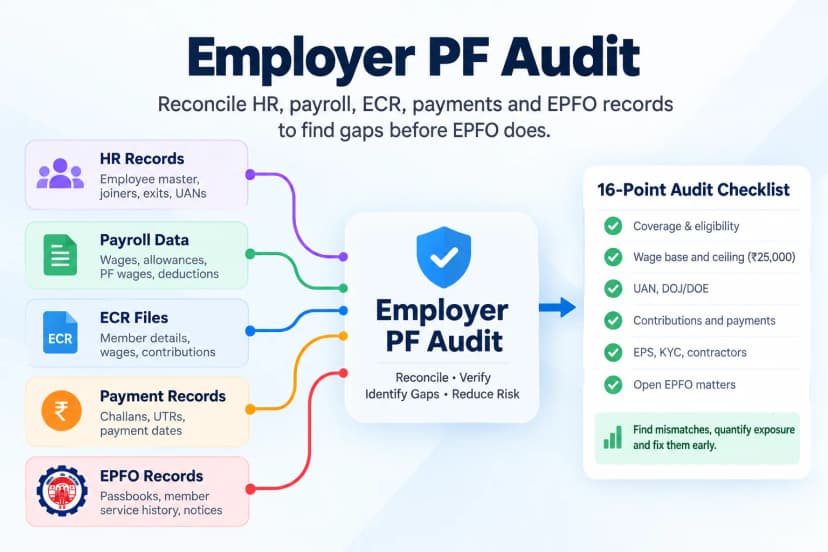
| Issues across the workforce | Employer PF compliance audit |
How Kustodian handles EPFO notices
Kustodian has handled 100+ employer engagements. In one, an EPFO notice showed a ₹2 lakh PF liability reappearing in the employer's financials. Wage reconciliation, payment tracing and re-filing closed it with zero penalty.
What we need: the notice, its deadline or hearing date, the establishment code, the period and the approximate number of employees.
What you get: a reconciliation of every employee-month named, a position on each allegation, the response and annexure pack, and representation at the hearing where needed.
EPFO notice FAQs
How long do I have to reply to an EPFO notice?
The date on the notice governs. For a s.137 direction, the compliance period it sets is the deadline that decides whether prosecution follows. If the date is too close to reconcile, ask in writing for time before it passes.
Is a Section 7A notice still valid in 2026?
Proceedings started under Section 7A before 21 November 2025 continue, and must conclude by 20 November 2027. New assessment notices are issued under s.125 of the Code on Social Security.
How far back can EPFO demand PF dues?
Under s.125, an inquiry cannot start more than five years after the amount became due. The old Section 7A had no such limit.
Can I settle a PF damages notice instead of contesting it?
For defaults before 14 June 2024, VISHWAS 2026 allows settlement at reduced damages rates until 28 December 2026. You must pay the interest first and undertake not to appeal further.
How much do I deposit to appeal an EPFO assessment?
25% of the amount determined under s.125, before the Tribunal hears the appeal. Unlike the old 75% rule, it cannot be waived.
Can the employer be held personally liable?
Recovery under s.129 goes first against the establishment's property. Only if that falls short can it move against the employer's own property, and arrest is one of the recovery modes.
Sources
- Code on Social Security, 2020, India Code (ss. 23, 122, 125, 127–129, 137)
- Employees' Provident Funds Scheme, 2026, G.S.R. 525(E), 29 June 2026, Gazette of India
- Interest notification S.O. 2698(E), 29 May 2026, Gazette of India
- Compliance Handbook for Employers under the Four Labour Codes, Ministry of Labour and Employment
- Assessment, recovery and compliance under the Code on Social Security, Taxmann, law as on 7 September 2026
This guide explains the general process. Formal proceedings should be assessed against the specific notice and current EPFO instructions.
PF Interest Loss Calculator
See how much interest you lose every month your claim sits unresolved.