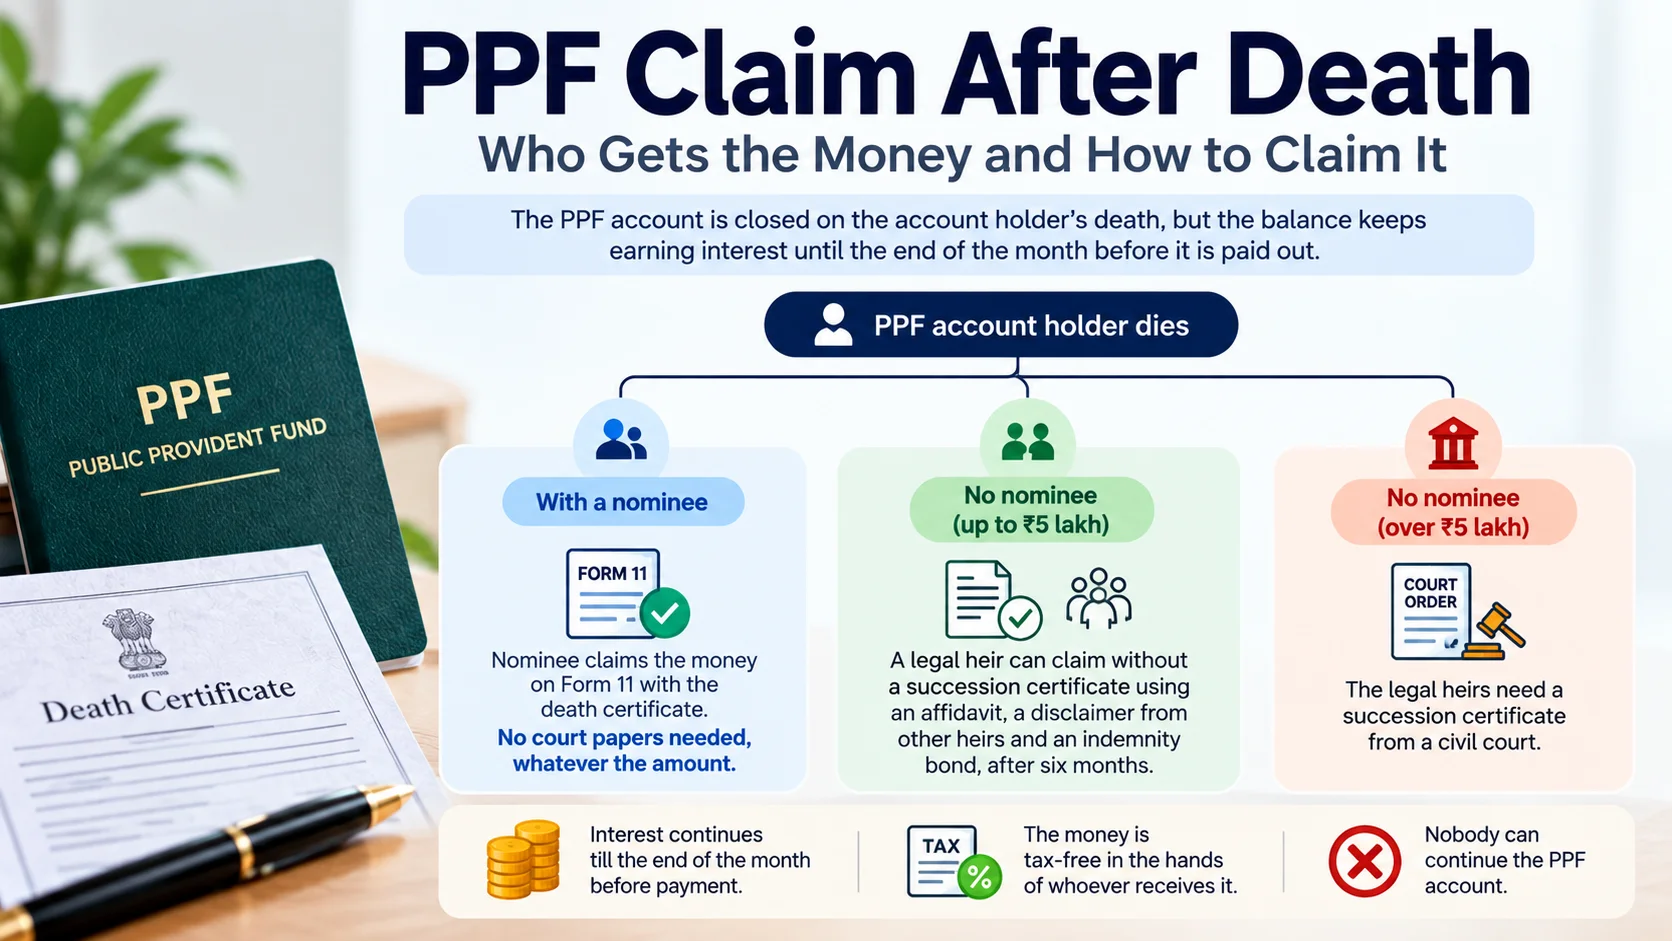
When a PPF account holder dies, the account is closed. Nobody can continue it, but the balance keeps earning interest until the end of the month before it is paid out.
- With a nominee: the nominee claims the money on Form 11 with the death certificate. No court papers are needed, regardless of the amount.
- Without a nominee, up to ₹5 lakh: a legal heir can claim it without a succession certificate, using an affidavit, a disclaimer from the other heirs, and an indemnity bond, once six months have passed since the death.
- Without a nominee, over ₹5 lakh: the branch needs legal proof of heirship. A legal heir certificate from the Tahsildar's office is enough; a court succession certificate or probate also works.
If any heir disputes the claim before payment, the branch will pay only against a court succession certificate, whatever the amount. The money is tax-free in the hands of whoever receives it.
Who gets the PPF money after the account holder dies?
The nomination on record decides who the branch pays. A holder can name one or more nominees, set each one's share, and say whether each nominee takes the money as owner or as trustee for the legal heirs. Check the nomination form or ask the branch for a copy.
| Situation at the time of death | Who is paid | Court papers needed? |
|---|---|---|
| One nominee | That nominee | No |
| Several nominees | In the shares the holder set, or equally if none were set | No |
| A nominee died before the holder | That nominee's share goes to the surviving nominees | No; add that nominee's death certificate |
| The nominee is a minor | The person the holder appointed to receive it, or else the minor's guardian | No |
| No nominee, balance up to ₹5 lakh | The legal heir who appears to be the rightful claimant | No; affidavit, disclaimer and indemnity bond instead |
| No nominee, balance over ₹5 lakh | The legal heirs | Not necessarily; a legal heir certificate from the Tahsildar, or a succession certificate or probate |
Sources: Government Savings Promotion General Rules 2018, rules 14 and 15 · PPF Scheme 2019, para 14
The same rules apply whether the PPF is at a bank or a post office, though each institution has its own forms and approval steps on top. A PPF can't be held jointly, so there is never a surviving joint holder to take it over.
No nominee? You may not need a succession certificate
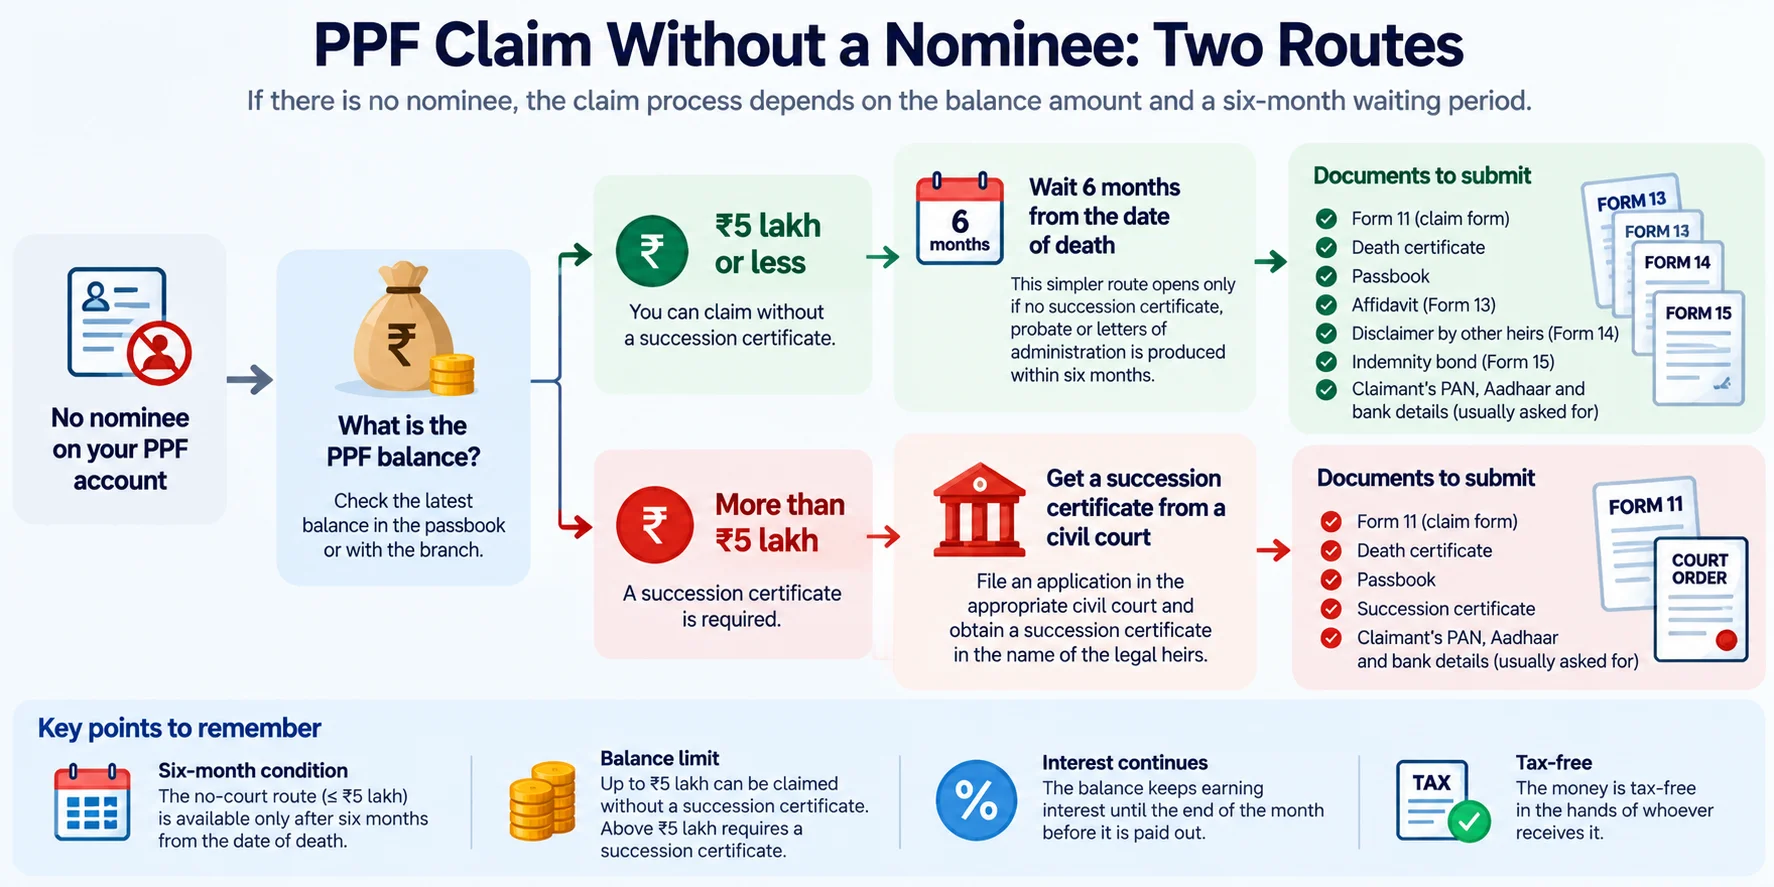
If there is no nominee and the balance is ₹5 lakh or less, the branch can pay the heir who appears to be the rightful claimant without court papers. Two conditions apply:
- Six months must pass from the date of death. The simpler route opens only if nobody has produced a succession certificate, probate, letters of administration or a legal heir certificate within those six months.
- The other heirs must agree in writing. That is what the disclaimer is for.
Above ₹5 lakh, the branch pays on legal proof of heirship. Since the July 2023 amendment to rule 15, a legal heir certificate from a revenue officer of Tahsildar rank or above is accepted, as well as a succession certificate, probate or letters of administration. If any heir disputes the claim before payment, the branch will pay only against a court succession certificate, whatever the balance.
Sources: Government Savings Promotion General Rules 2018, rule 15 (as substituted in July 2023) · India Post SB Order 36/2020
Example: your father's post office PPF holds ₹3.2 lakh. He named no nominee and died on 10 March 2026. From 10 September 2026, the heir the post office accepts as the rightful claimant can collect it with Form 11, the death certificate, the passbook, an affidavit, a disclaimer signed by the other heirs and an indemnity bond and their own identity proof. No court is involved.
If a branch asks for a succession certificate on a balance under ₹5 lakh, ask them to check rule 15 before you go to court. A succession certificate can take months and costs court fees. Above ₹5 lakh, ask whether a legal heir certificate from the Tahsildar will do instead; getting one does not involve a court.
No nominee, and the branch is asking for court papers?
We check the balance, the heirs and the dates, tell you which route applies, and prepare the affidavit, disclaimer and indemnity bond. If you can do it yourself, we'll say so first.
How to claim a PPF after death
- Find out where the account is held. The passbook names the bank branch or post office. The claim goes to that office.
- Get the death certificate, plus a few self-attested copies.
- Fill in Form 11, the current claim form for nominees and legal heirs under the Government Savings Promotion Rules, 2018.
- Submit it with the documents for your route (table below) and keep the acknowledgement slip with the date.
The money is paid into the claimant's bank or post office savings account. Interest runs until the end of the month before payment, so a slow claim doesn't cost interest, but it does cost time.
| Your route | Required by the rules | Usually also asked for |
|---|---|---|
| Nominee | Form 11, death certificate | Passbook, nominee's PAN, Aadhaar and bank details |
| Nominee, where another nominee died earlier | Form 11, both death certificates, the surviving nominee's identity proof | Passbook and bank details |
| No nominee, up to ₹5 lakh | Form 11, death certificate, passbook, affidavit (Form 13), disclaimer by the other heirs (Form 14), indemnity bond (Form 15), the legal heir's identity proof | Claimant's PAN and bank details |
| No nominee, over ₹5 lakh | Form 11, death certificate, passbook, the legal heir's identity proof, and one of: legal heir certificate (Tahsildar or above), succession certificate, probate or letters of administration | Claimant's PAN and bank details |
Lost the passbook? Tell the branch when you submit; they will tell you what to give in its place.
Sources: Government Savings Promotion General Rules 2018, rule 15 (as substituted in July 2023) · Form 11, National Savings Institute · PPF Scheme 2019, para 14
How long it should take: India Post's SB Order 01/2023 (9 January 2023) tells post offices to settle claims within 1 working day where there is a nominee and 7 working days in other cases, when the amount is within their own sanction limit. It also says the branch shouldn't send you back for bank details or ask witnesses to appear in person if their signatures are on KYC copies. Source: India Post SB Order 01/2023
Nominee or legal heir: who actually owns the money?
Paying the nominee settles things with the branch. Whether the nominee keeps the money depends on what the nomination says. Under rule 14, the holder can mark each nominee as:
| Nomination says | What it means |
|---|---|
| Owner | The nominee keeps the money outright |
| Trustee | The nominee receives it for the legal heirs and must pass it on |
| Nothing (older PPF nominations made under the pre-2018 rules had no such field) | The Supreme Court has held that a nominee of government savings only receives the money for the legal heirs (Vishin N. Khanchandani v. Vidya Lachmandas Khanchandani, 2000) |
Source: Government Savings Promotion General Rules 2018, rule 14 and Form 10
If the family disagrees about who should end up with the money, that is a legal question, not part of the claim. If the dispute is raised before payment, the branch will pay only against a court succession certificate. Speak to a lawyer before anyone signs a disclaimer.
PPF death claim rejected or delayed? Match what you're hearing
| What the branch says | Usual reason | What to do |
|---|---|---|
| "Bring a succession certificate" on a balance under ₹5 lakh | Six months haven't passed, or the branch isn't applying rule 15 | Check the date of death; if six months have passed, ask them to apply rule 15 in writing |
| "The name doesn't match" | Spellings differ across passbook, death certificate and ID | An affidavit stating both names belong to the same person |
| "All heirs must sign" | The disclaimer is missing a signature | Get it signed, or apply for a succession certificate if an heir refuses |
| "The account is frozen" | The deceased's PPF was frozen before death | Frozen or inactive PPF |
| No reply after 7 working days | The file is waiting at the divisional office | Ask for the status in writing, citing SB Order 01/2023, or get the case reviewed |
| Branch keeps sending you back | Often a records problem nobody has named | Get the case reviewed |
Do you need help?
A nominee with a death certificate and passbook usually doesn't. It's worth getting help when there is no nominee, an heir lives abroad or won't sign, the account is frozen, or the branch has rejected the claim without a clear reason.
Get my PPF case reviewed. We tell you the route, the documents and the blocker, and say plainly if you can do it yourself.
Questions families ask about PPF death claims
Which form is used for a PPF death claim?
Form 11, the claim form for nominees and legal heirs under the Government Savings Promotion Rules 2018. It replaced the old PPF claim form, Form G, though some bank branches still hand out Form G.
Do I need a succession certificate to claim a PPF above ₹5 lakh?
Not necessarily. Since the July 2023 amendment to rule 15 of the Government Savings Promotion General Rules, the branch can pay a balance above ₹5 lakh against a legal heir certificate from a revenue officer of Tahsildar rank or above, as well as a succession certificate, probate or letters of administration. If any heir raises a dispute before payment, a court succession certificate is required.
Can the nominee continue the deceased person's PPF account?
No. The account is closed on the holder's death, and neither the nominee nor a legal heir can continue it. The balance earns interest until the end of the month before it is paid.
Is the PPF amount taxable for the nominee or legal heir?
No. PPF payments are exempt under Schedule II (item 3) of the Income-tax Act, 2025, in force from 1 April 2026. Before that, the same exemption sat in section 10(11) of the 1961 Act.
How long does a PPF death claim take?
At a post office, India Post's guidelines set 1 working day where there is a nominee and 7 working days in other cases, for claims within the post office's sanction limit. Without a nominee, the simpler route for balances up to ₹5 lakh opens only six months after the death.
What if the deceased's PPF had matured years ago?
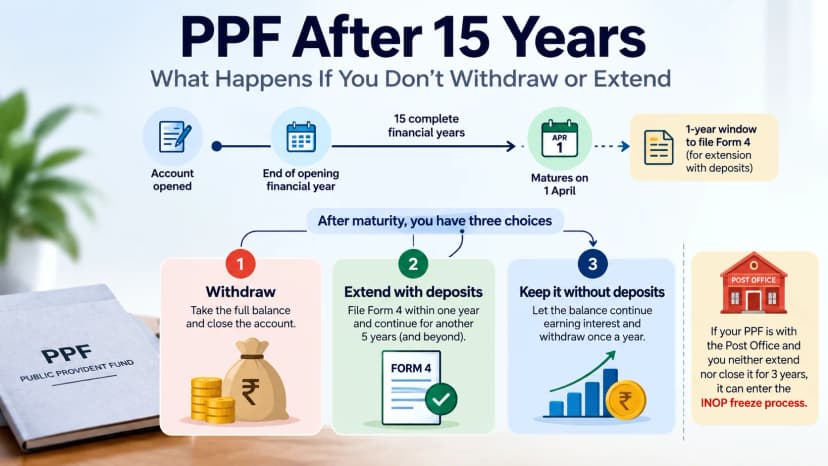
The money is still payable to the nominee or heirs. If it is a post office account left untouched for more than 3 years after maturity, it may be frozen, which adds a step before payment. See frozen post office PPF and PPF after 15 years.
Sources and how we checked
We checked every rule on this page against the primary text on 20 November 2026.
- Government Savings Promotion General Rules, 2018: rule 14 and Form 10 (nomination, shares, owner or trustee)
- Rule 15, payment on death, as substituted by G.S.R. 488(E), 3 July 2023: ₹5 lakh limit, six months, legal heir certificate, dispute rule, Forms 11, 13, 14 and 15
- Form 11, National Savings Institute: claim form for nominees and legal heirs
- Public Provident Fund Scheme, 2019, para 14: account closed on death, interest until payment
- India Post SB Order 01/2023, SB Order 01/2023, 9 January 2023: 1 and 7 working-day settlement
- India Post SB Order 36/2020, 6 November 2020: sanction limits and the ₹5 lakh succession certificate rule
- Income-tax Act, 2025, Schedule II: exemption for PPF payments
- Vishin N. Khanchandani v. Vidya Lachmandas Khanchandani, Supreme Court of India, 2000: nominee of government savings holds for legal heirs
First published: 20 November 2026.
Related: Nominee vs legal heir · PPF after 15 years · Succession certificate basics
PF Interest Loss Calculator
See how much interest you lose every month your claim sits unresolved.