Last checked 20 November 2026 against the PPF Scheme 2019 and SBI's PPF FAQ
A PPF becomes "discontinued" when you miss the ₹500 minimum deposit in any financial year. You can reactivate it any time before it matures by paying the missed ₹500 for each year plus a ₹50 fee, which banks such as SBI charge for each missed year: ₹550 per missed year.
Until you do, the balance still earns interest, but you can't take a loan or partial withdrawal, can't open a new PPF, and can't extend it with deposits after 15 years. After maturity, revival is no longer possible.
Check the cause first. If the branch is asking for Aadhaar or PAN, or it's a matured post office account, paying arrears won't fix it.
Which "inactive" is yours? · How to reactivate · If you don't revive it · Already past maturity? · Questions
Which "inactive" is your PPF?
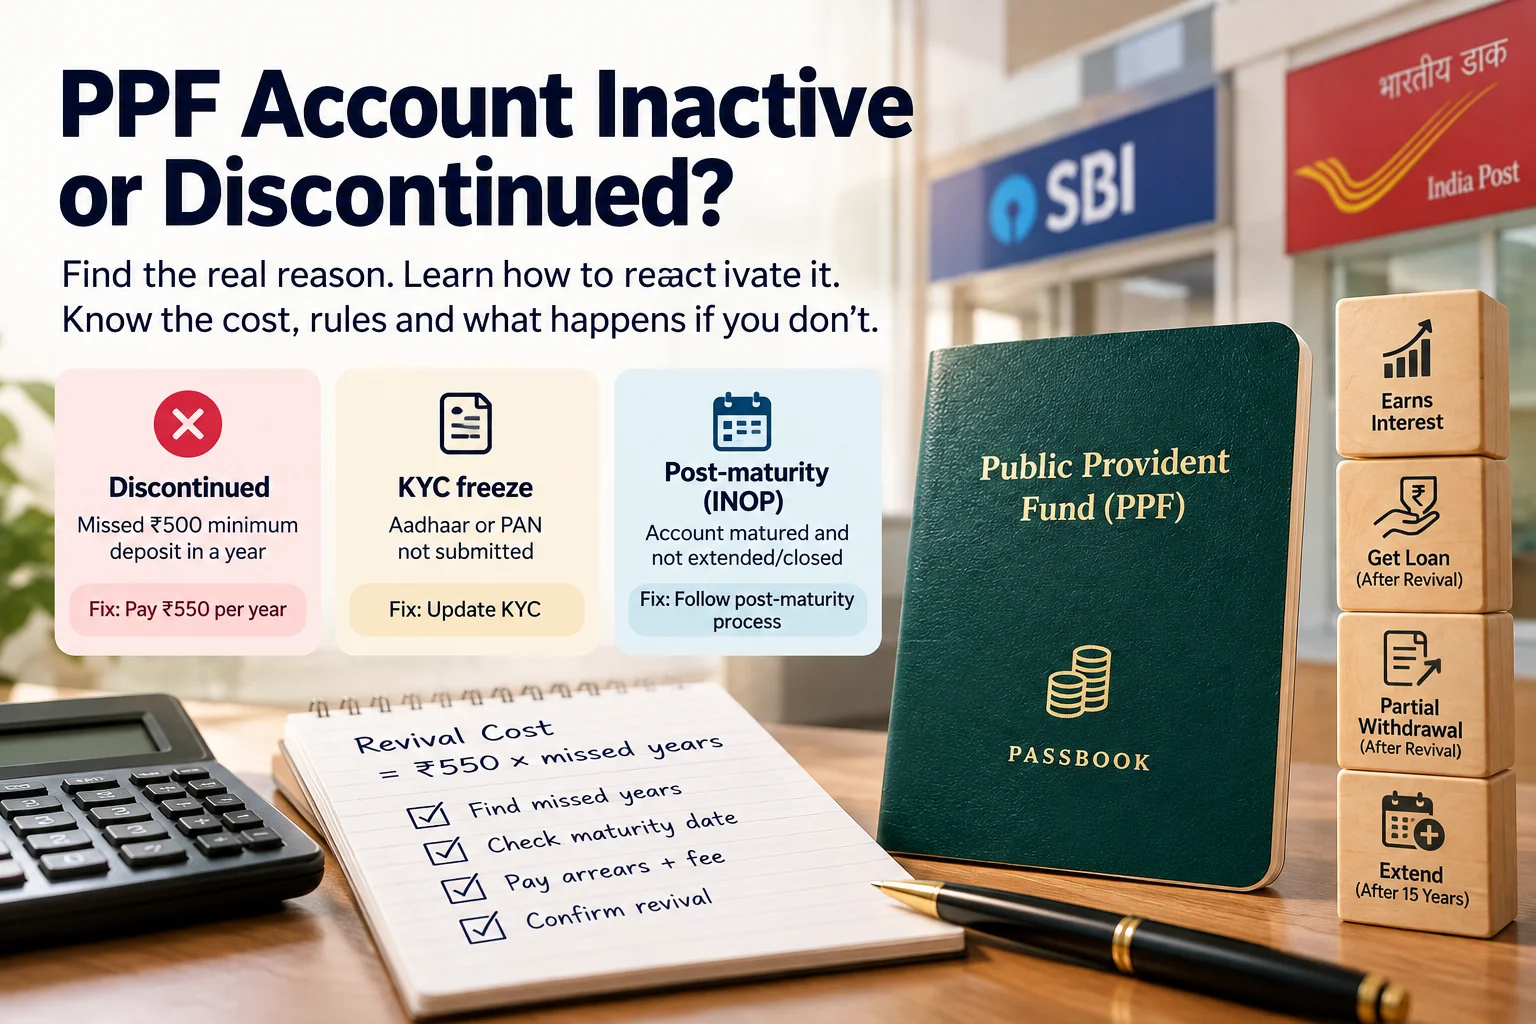
Banks and post offices use "inactive" for three different problems. Only one of them is fixed by paying arrears.
| What you see | Real cause | The fix | Fixed by paying ₹550 a year? |
|---|---|---|---|
| "Discontinued" or inactive, account not yet 15 years old | You missed the ₹500 minimum in one or more financial years | Pay the arrears and fee (below) | Yes |
| Frozen or inactive, and the branch asks for Aadhaar or PAN | KYC never submitted; small savings accounts without Aadhaar were frozen from 1 October 2023 | Submit Aadhaar and PAN at the branch | No |
| Post office passbook or system shows "INOP" | The account matured and wasn't extended or closed within 3 years | Unfreeze at the branch: frozen post office PPF | No |
Not sure which? Ask the branch for the status in writing and the year-wise deposit history. Missing years in that history mean it's the first row.
Branch says "inactive" but can't tell you which kind, or the missed years don't add up?
We get the year-wise statement, tell you the exact fix and what it should cost, and say so if you can do it yourself.
How to reactivate a discontinued PPF
The rule is in para 6 of the PPF Scheme 2019: a discontinued account "may be revived during its maturity period" by paying the ₹500 minimum for each year of default plus a ₹50 fee. Banks such as SBI charge that ₹50 for each missed year, so budget ₹550 per missed year and confirm the total with your branch.
Sources: PPF Scheme 2019, para 6 (India Post) · SBI PPF FAQ
Revival cost = ₹550 × the number of missed financial years
- Find the missed years. Go through the passbook financial year by financial year (April to March). Any year without at least ₹500 counts. If the passbook is incomplete, ask the branch for the year-wise statement.
- Check the deadline. Revival is only allowed before maturity, which is 1 April after 15 full financial years. Find your maturity date.
- Pay at the branch that holds the account. Take the passbook and ask for revival of the discontinued account. Pay the arrears and fees together, and make this year's ₹500 deposit as well so the account doesn't fall behind again.
- Check the passbook. The next entries should show the arrears and the fee. Ask the branch to confirm the account is now regular.
Example: you opened a PPF in FY 2012-13 and last deposited in FY 2019-20. The missed years are 2020-21 to 2025-26, which is 6 years. Revival costs 6 × ₹550 = ₹3,300. The account matures on 1 April 2028, so the last day to revive it is 31 March 2028.
Only ₹300 of that is a fee. The ₹3,000 of arrears are deposits that stay in your account and earn interest like any other.
What happens if you don't revive it?
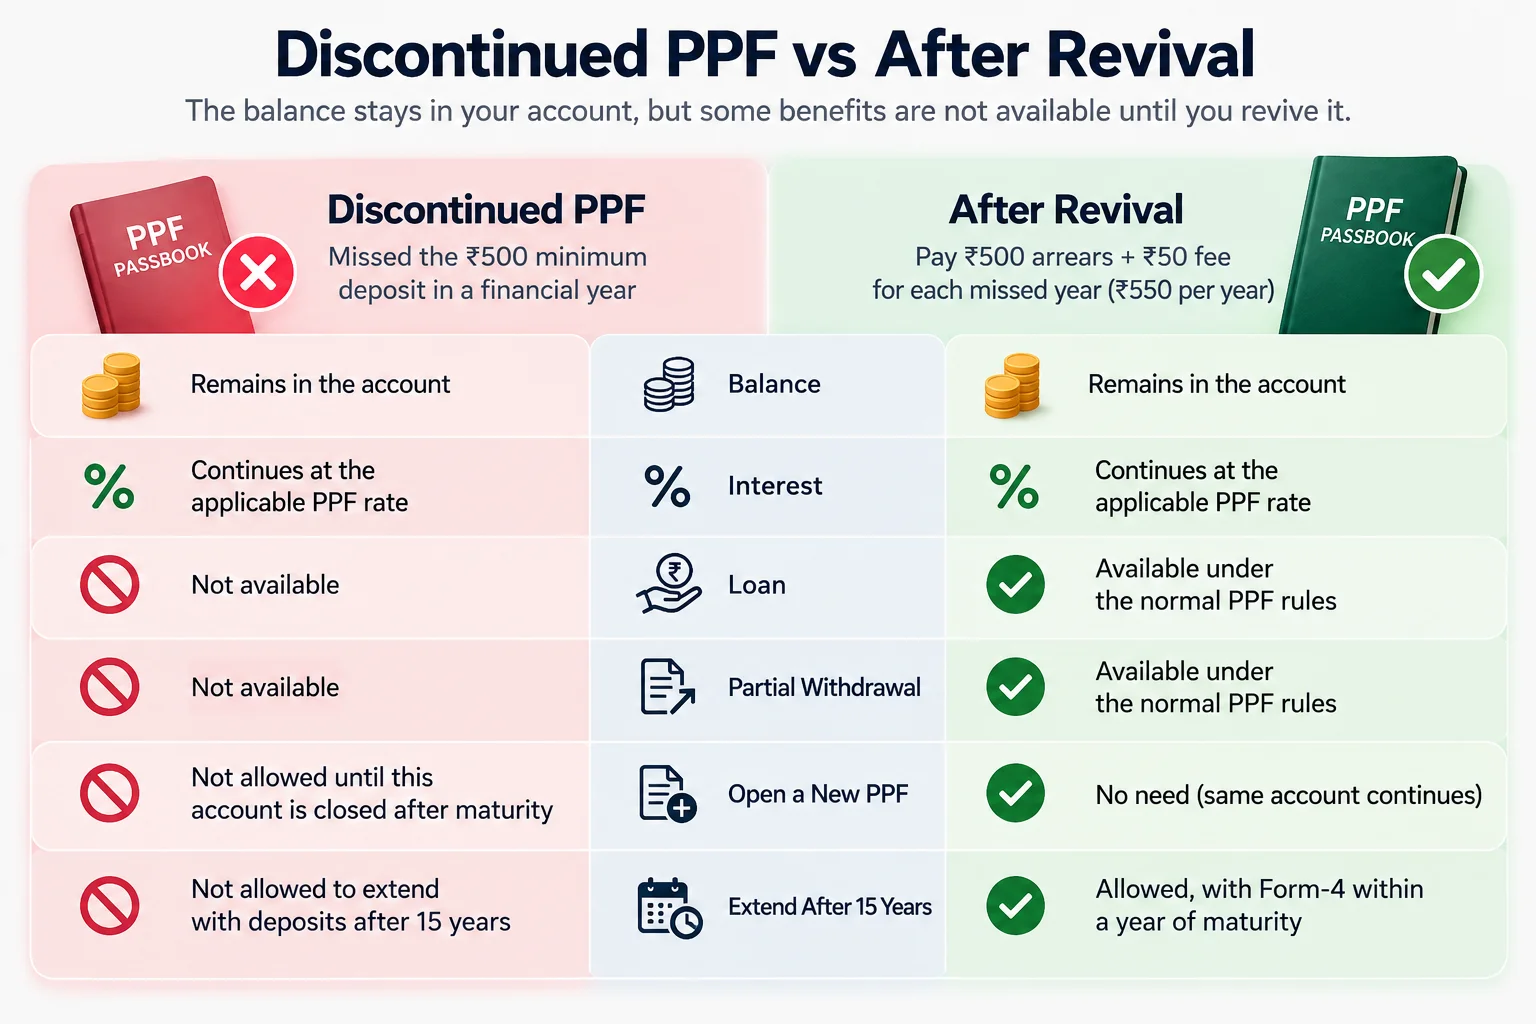
The money isn't lost, but the account is stuck in a reduced state until it matures.
| Discontinued PPF | After revival | |
|---|---|---|
| Balance | Stays in the account | Stays in the account |
| Interest | Continues at the PPF rate | Continues at the PPF rate |
| Loan or partial withdrawal | Not allowed | Allowed under the normal rules |
| Open a new PPF | Not allowed until this one is closed after maturity | Not needed |
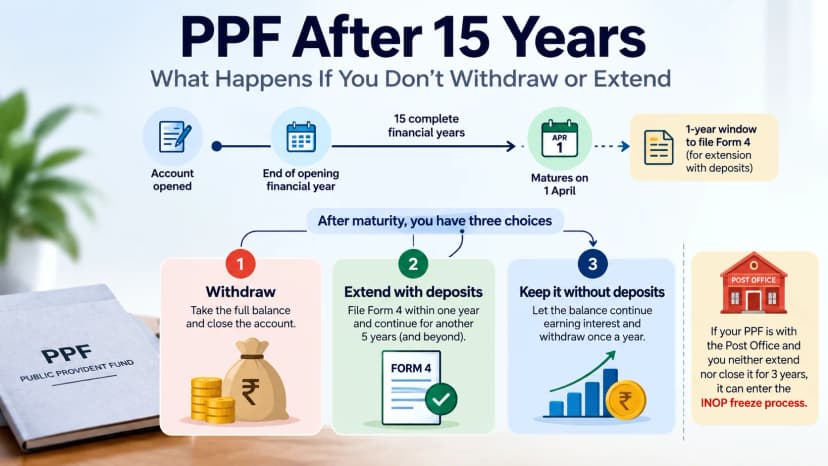
| Extend with deposits after 15 years | Not allowed | Allowed, with Form-4 within a year of maturity |
Sources: PPF Scheme 2019, para 6 · SBI PPF FAQ
For most people, ₹550 a year is a small price for getting the loan, withdrawal and extension options back.
Already past maturity?
Then revival is closed. The account can still be withdrawn in full, or kept without deposits, but not extended with deposits. See your options after 15 years and, if you want to withdraw, how to close a matured PPF.
Questions about inactive PPF accounts
Can I open a new PPF instead of reviving the old one?
No. The PPF Scheme bars the holder of a discontinued account from opening a new one until the discontinued account is closed after maturity. One person can hold only one PPF in their own name.
Can a discontinued PPF be extended after 15 years?
Only if you revive it before maturity. SBI's PPF FAQ says only accounts that matured with regular deposits, or were regularised before maturity, can be extended with deposits.
Does a discontinued PPF still earn interest?
Yes. The balance keeps earning interest at the PPF rate, whether or not you revive it.
Is the revival fee different at banks and post offices?
Usually not. The ₹500 arrears for each missed year come from the PPF Scheme. The scheme text mentions a ₹50 fee, and SBI charges it for each missed year. Ask your branch or post office to confirm the total before you pay.
Can I reactivate my PPF online?
Ask your bank. SBI's FAQ doesn't describe an online revival route, so plan on doing it at the branch that holds the account.
Sources and how we checked
We checked every rule on this page against the primary text on 20 November 2026.
- Public Provident Fund Scheme, 2019 (India Post copy): para 6 (discontinued accounts, revival, no new account)
- National Savings Institute: Public Provident Fund: scheme summary
- SBI: Public Provident Fund FAQ: ₹50 penalty, extension only for regular accounts
- Aadhaar and PAN made mandatory for small savings (Business Today, April 2023): KYC freeze rule
- India Post SB Order 25/2022 (16 December 2022): post office freeze ("INOP") of matured accounts not closed within 3 years
Updated: 20 November 2026.
Related: PPF after 15 years · PPF claim after death
PF Interest Loss Calculator
See how much interest you lose every month your claim sits unresolved.